Almost everyone heading to Australia for a Working Holiday, study or work runs into the same question: “Do I actually need insurance?” Search online and you'll find OSHC, OVHC, travel insurance — a dizzying pile of English acronyms! Choose wrong and you may not be covered when it counts, or you could be hit with a huge bill when you see a doctor — heartbreaking and painful for your wallet.
Do you really need insurance for Australia? Get it wrong and it could cost you! Here's why insurance matters so much in Australia 👇
Almost everyone heading to Australia for a Working Holiday, study or work runs into the same question: “Do I actually need insurance?”
Search online and you'll find OSHC, OVHC, travel insurance — a dizzying pile of English acronyms! Choose wrong and you may not be covered when it counts, or you could be hit with a huge bill when you see a doctor — heartbreaking and painful for your wallet.
Why should you consider insurance for Australia? (Do you need insurance for Australia?)
If you're preparing for a Working Holiday, study or short-term work, one question may be on your mind: “Do I really need insurance to go to Australia?”
The answer: it's not just recommended — in many cases, it's a “must”!
Here's why insurance matters so much in Australia 👇
Why should you consider insurance for Australia?
(Do you need insurance for Australia?)
If you're planning a Working Holiday, a trip, language school or a new job in Australia, the most practical question is: “Do I actually need health insurance?”
This isn't an unnecessary question: Australia's healthcare system and costs are very different from Taiwan's, and one slip can leave a big hole in your wallet. Here are three reasons why insurance is something you should never skip.
Medical costs in Australia are shockingly high
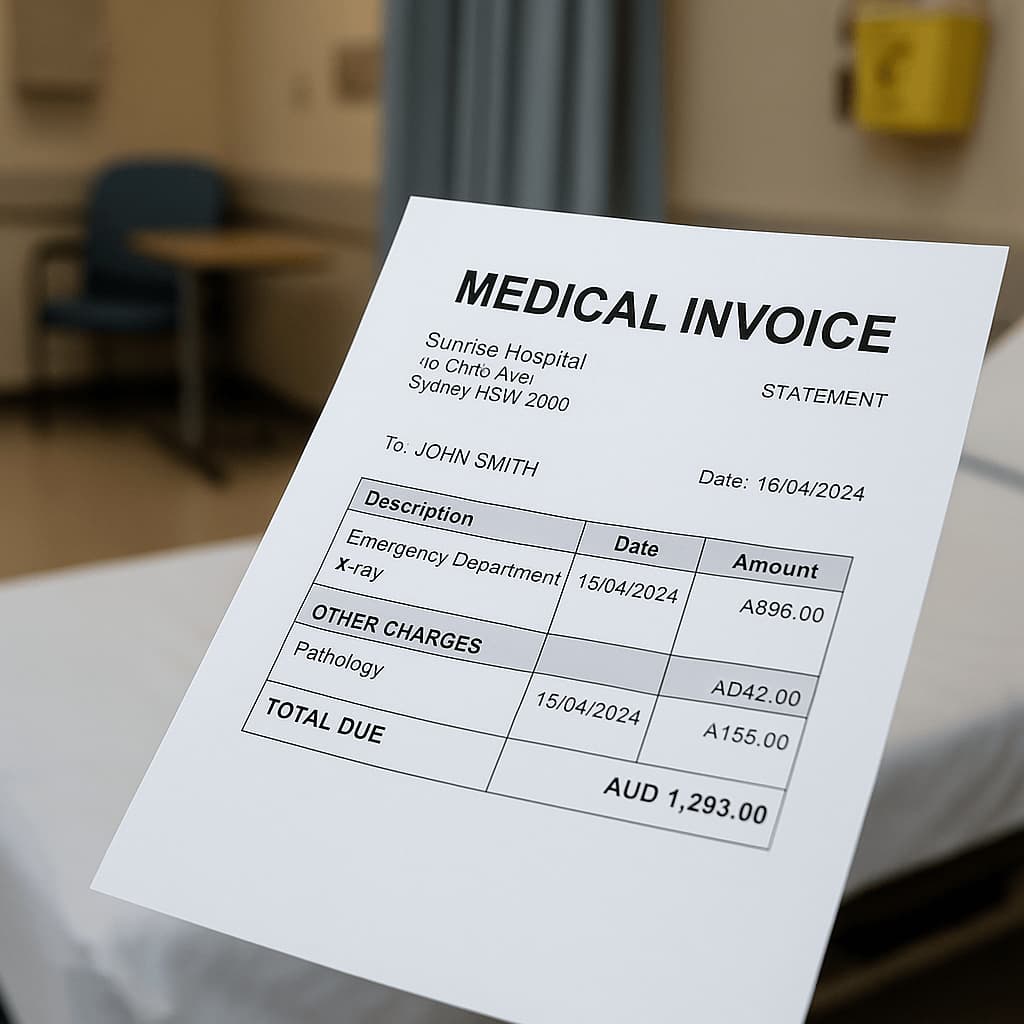
Australia's medical care is excellent, but there's “no universal coverage” for non-residents, so every doctor's visit comes out of your own pocket:
- 👨⚕️ Seeing a general practitioner (GP): about AUD $80–$120
- 🏥 A trip to the emergency room: from AUD $300
- 🛏️ One day in hospital: easily AUD $1,500–$3,000
- 🚑 One ambulance trip: AUD $600–$1,000 (varies by state)
Even for a common cold or a sprain, without insurance you could spend a week’s wages or more — and if it’s an accident or a chronic illness, the costs can be catastrophic.
The real risks of no insurance
Many people think, “I'm very healthy, so I probably won't need insurance.” But in reality, changes in lifestyle and diet abroad, adjusting to a new environment, or traffic accidents are all things you can't predict.
Without insurance, you may face the following risks:
- ❌ The hospital may refuse treatment or demand a full deposit upfront
- ❌ No reimbursement for any medication or emergency costs
- ❌ Unable to get proper treatment promptly in an emergency (e.g. car accident, infection)
- ❌ It can even affect your visa application, extension and legal status
Simply put, no insurance = one accident becomes a financial crisis.
Insurance requirements by visa type
In Australia, your visa type directly determines whether you “must” buy insurance:
| Visa type | Insurance mandatory? | Recommended insurance type |
|---|---|---|
| Student visa (Subclass 500) | ✅ Mandatory | OSHC |
| Employer-sponsored work visas (Subclass 482, etc.) | ✅ Mandatory | OVHC |
| Working Holiday visa (417/462) | ❌ Not mandatory, but recommended | OVHC |
| Tourist / visitor visa | ❌ Not mandatory, but recommended | OVHC |
Although insurance isn't legally required for Working Holiday or tourist visas, the Australian Government clearly recommends that all visitors have insurance.
You can choose not to buy it, but if something happens, you'll bear all the consequences yourself.
So, do you really need insurance for Australia?
If you want to protect your health and your financial freedom, the answer is simple: of course you do!
Now let's take a closer look at the different insurance options: what is OSHC, and who is OVHC for?
What is OSHC? | Essential health cover for international students
(What is OSHC? Recommended insurance for international students in Australia)
If you're heading to Australia on a student visa — whether for a language school, vocational college or university — OSHC is one of the things you absolutely must sort out before you leave.
Many students only discover when they first apply for a visa that “insurance isn’t optional — it’s a requirement.” So what exactly is OSHC? Here’s everything you need to know👇
Coverage overview
OSHC (Overseas Student Health Cover) is health insurance designed for international students and required by the Australian Government: all student visa holders must buy it, or their visa won't be granted.
It mainly helps cover basic medical expenses during your time in Australia, including:
- 👨⚕️ General consultations (seeing a family doctor, GP)
- 🏥 Hospital costs (surgery, treatment, etc.)
- 💊 Prescription medicine subsidies (not all medicines)
- 🧪 Medical tests (e.g. blood tests, X-rays)
- 🚑 Ambulance services (only with some insurers)
⚠️ **Not included:** dental, optical, counselling, physiotherapy and other non-basic medical care. If you need these, you'll have to buy an add-on policy.
Who it's for and how to buy
Who it's for:
- International students on a student visa (Subclass 500)
- All students enrolled in language school, college, university or postgraduate courses
- Accompanying family members (additional Dependent Cover required)
There are two ways to buy:
- 🏫 Through your school: buy insurance together with your school application (from the school's partner insurers, such as Bupa, Allianz, nib, etc.)
- 💻 Buy online yourself: choose the plan and coverage period that suit you on the insurer's website
Buy it in advance and make sure the policy covers your entire study period (including the buffer before enrolment and after graduation).
Mandatory? Risks of non-compliance
OSHC is a mandatory requirement set out by Australian immigration authorities. Without OSHC, you face the following risks:
- ❌ Unable to lodge your student visa application
- ❌ If your cover lapses after your visa is granted, it may affect your visa's validity or lead to cancellation
- ❌ No cover when you see a doctor; you pay all medical costs yourself
Simply put, OSHC isn't just protection — it's one of your tickets to studying in Australia legally.
So if you're an international student about to set off, be sure to sort out OSHC first. It's not only a legal requirement but also the first step to protecting your health and finances!
Next, let's look at a different situation: what if you're not a student? That's when you need OVHC!
What is OVHC? | For Working Holiday makers, travellers and workers
(What is OVHC? Recommended insurance for Working Holiday in Australia)
Does not being on a student visa mean you don't need insurance? Quite the opposite!
If you're coming to Australia on a Working Holiday, tourist or short-term work visa, you'll need to know about a different type of insurance: OVHC (Overseas Visitors Health Cover).
Who it's for and common plans
OVHC is health insurance designed for non-student visa holders, including:
- Working Holiday visa (Subclass 417 / 462)
- Visitor Visa
- Employer-sponsored work visas (e.g. Subclass 482)
- Dependent Visa
Common OVHC plans vary by insurer and level. Leading insurers include:
- ✅ Bupa OVHC: comprehensive cover and many service locations
- ✅ Allianz Care: suited to short-term work and WHV holders
- ✅ Medibank OVHC: flexible plans, good for long-term workers
- ✅ nib OVHC: relatively affordable, good for tighter budgets
These plans come in different tiers to suit your budget and needs. The more you pay, the more comprehensive the cover, but plenty of basic plans still meet essential medical needs.
What's covered, and recommended extra cover
OVHC basic cover usually includes:
- 👨⚕️ GP (family doctor) consultation fees
- 🏥 Hospital and surgery costs
- 💊 Partial subsidy for prescription medicines
- 🚑 Ambulance (included in some plans)
But there are also some advanced benefits that are worth adding:
- 🦷 Dental and optical (mostly not included)
- 🤕 Accident or travel accident cover
- 🏥 Specialist outpatient care, counselling
- 🏄♂️ Outdoor activity injury cover (e.g. high-risk activities such as skiing and diving)
📌 Quick tip: every insurer has a “waiting period”, meaning some benefits only take effect after you've held the policy for a while. Be sure to read the terms carefully before you leave.
Do you really need OVHC for a Working Holiday?
Legally speaking, Working Holiday visa holders aren't necessarily “required” to buy OVHC. But in practice, “strongly recommended” is almost the same as essential.
There are three reasons:
- Medical costs in Australia are very high; without insurance, a single emergency visit could cost you a week's wages.
- If you have an accident at work, your employer may not cover all of your medical costs.
- Insurance is one of the key supporting documents when extending or changing your visa, and helps with your future plans to stay in Australia.
The Australian Department of Home Affairs also clearly recommends:
“We recommend all visitors to Australia arrange adequate health insurance.”
In a nutshell: you can skip it, but you carry all the risk yourself.
All in all, OVHC is a Working Holiday maker's raincoat. You may not seem to need it day to day, but when you really do, it'll be your most worthwhile investment.
Next, we'll use a table to clearly compare OSHC and OVHC, helping you decide faster!
OSHC vs OVHC: what's the difference? A complete comparison to avoid costly mistakes
(What's the difference between OSHC and OVHC? Australian insurance compared)
OSHC and OVHC differ by just one letter, but in practice their eligibility, coverage and whether they're mandatory are completely different. Many people mix them up and end up either buying insurance that doesn't apply to them or having their visa held up — a costly mistake.
Here we've summed it all up for you, so you choose the right insurance and avoid the pitfalls!
🎯 Eligible visas vs coverage vs mandatory status
| Comparison item | OSHC | OVHC |
|---|---|---|
| Eligible visas | Student visa (Subclass 500) | Non-student visas such as Working Holiday, tourist and work visas |
| Main users | International students | Backpackers, travellers, short-term workers |
| Mandatory? | ✅ Mandatory (visa requirement) | ❌ Not mandatory (with some work visa exceptions) |
| Coverage | Basic medical, hospital, prescription medicines (conditions apply) | Medical, hospital and emergency care; some include ambulance |
| Quality of care | Both valid at public and private medical facilities in Australia | Same as above, but more flexible depending on the plan |
📌 Quick tip: when applying for a student visa, your visa won't be approved without proof of OSHC; for Working Holiday makers it isn't mandatory, but going without it is very risky.
💰 Differences in price and claims process
| Item | OSHC | OVHC |
|---|---|---|
| Premium range | About AUD $40–60/month (relatively stable) | About AUD $40–120/month (varies with coverage) |
| How claims work | Usually direct billing or reimbursement of actual costs | Depending on the policy terms, you can claim or offset costs |
| Waiting period | Usually shorter | Some items (e.g. pregnancy, dental) have longer waiting periods |
| Extra add-on cover | More restrictions; extras must be purchased separately | More flexible, with optional extras (e.g. outdoor sports accidents) |
👉 Tip:
- OSHC suits students who don't want to spend time comparing plans
- With OVHC, you choose the insurer and level of cover that suit your needs. Prices and coverage vary a lot, so shop around
❗ Common mistakes and myths debunked
❌ Mistake 1: I'm on a student visa, but a friend said OVHC is cheaper, so I bought that.
➡️ Wrong! Student visa holders can only buy OSHC; buying OVHC is a waste of money and won't get your visa approved.
❌ Mistake 2: My Working Holiday is only three months, so I probably won't need insurance, right?
➡️ Colds, cuts, allergies, food poisoning, sprains… they're really common, and a single medical bill can cost more than a month's premium, so not buying insurance is a bad deal.
❌ Mistake 3: Travel insurance is enough, so I don't need OVHC, right?
➡️ Wrong! Travel insurance mostly covers short-term accidents and losses; it doesn't necessarily cover hospital and treatment costs within the Australian healthcare system, and local hospitals may not accept it.
✅ The right approach:
- International students should simply buy OSHC to keep their visa secure
- On a Working Holiday or work visa? Compare OVHC policies and choose one that includes the cover you need
The conclusion: which insurance you should buy depends entirely on your visa and your purpose in Australia.
Buying the wrong one isn't just a waste of money — it could leave you with no protection when you need medical help the most!
Next, let's look at what can actually happen without insurance — a few real cases will make it hit home!
For the working holiday visa's own requirements and documents, see Australian Working Holiday Visa: Requirements and Documents at a Glance.
Real cases: going without insurance is truly scary!
(Risks of no insurance in Australia; seeing a doctor in Australia is expensive)
Many people think, “I'm healthy, so I probably won't need insurance.” But when living in Australia, medical expenses often come quickly and suddenly.
The real cases below show just how difficult and expensive things can get without insurance.
🧑🦽 Case A: sprained hand, no insurance, full medical bill paid out of pocket
Amy, a Working Holiday backpacker from Taiwan, was working at a café. One day, Amy slipped on the wet floor and ended up with a sprained wrist that was swollen and very painful.
At the local hospital, the treatment included:
- Initial GP consultation: AUD $95
- X-ray: AUD $180
- Simple splint and medication: AUD $60
The total came to over AUD $335 (about NT$7,000), all paid out of pocket — without insurance, not a cent could be reimbursed. And that was only a minor injury; a fracture or surgery would multiply the cost.
🚑 Case B: a traveller with no insurance hit with a huge emergency bill
Lisa, an independent traveller visiting Australia on a tourist visa, suddenly had stomach pain and vomiting early one morning and was taken to the emergency department.
The hospital provided the following:
- Emergency registration and treatment fee: AUD $320
- Blood tests and ultrasound: AUD $450
- Medication and IV fluids: AUD $80
- Observation bed (4 hours): AUD $600
The total cost came to AUD $1,450 (about NT$30,000)
With no OVHC or other acceptable insurance, the hospital required full payment on the spot before discharge.
The bill cut her trip short, and she even had to ask her family for help to pay it.
📊 With vs without insurance: the real difference
| Item | With insurance (OSHC/OVHC) | No insurance |
|---|---|---|
| GP visit | AUD $20–$40 out-of-pocket (some fully reimbursed) | AUD $80–$120, fully self-paid |
| Emergency treatment | Depends on the plan; often fully or partly covered | From AUD $300–$600 |
| Hospital stay | Can reimburse part or all of hospital costs (depending on the policy) | From AUD $1,500/day |
| Ambulance | Offered by most plans | AUD $600–$1,000 per trip |
| Stress level | ✅ See a doctor with peace of mind, no fear of medical bills | ❌ Afraid to see a doctor; high stress |
The conclusion is simple: insurance isn't about whether you'll use it — it's about whether you're prepared for the unexpected.
In Australia, high medical costs aren't a scare tactic — they're a fact.
Don't let a single doctor's visit bankrupt your whole trip or life there.
Next, we'll show you how to choose the right plan for your needs, so you get the best balance between budget and coverage!
How to choose the right insurance plan: 4 key points for beginners
(How to choose health insurance in Australia: recommended plans compared)
Now that you understand the difference between OSHC and OVHC, the next step is: how do you choose an insurance plan that really suits you?
Whether you're a student, a Working Holiday maker or a newcomer staying in Australia short term, these 4 key points will help you avoid the pitfalls and choose the right policy!
1️⃣ Choose your insurance type based on your visa and travel goals
What visa do you hold? How long will you stay in Australia? What will you mainly be doing?
These answers directly determine which insurance you should buy:
| Visa type | Recommended insurance |
|---|---|
| Student visa (Subclass 500) | ✅ OSHC (mandatory) |
| Working Holiday visa (417/462) | ✅ OVHC (not mandatory but strongly recommended) |
| Work visas (e.g. 482) | ✅ OVHC (often a visa condition) |
| Tourist / family visit visa | ✅ OVHC (protects against unexpected medical bills) |
🧭 Quick tip: even if you're only staying three months, one cold or emergency visit can cost far more than three months of premiums.
2️⃣ Weigh coverage against premium
Don't just look at the monthly premium — also ask yourself:
- Does it cover doctor visits, emergency care, hospital stays and medication?
- Do you need extra cover for dental, optical, counselling or pregnancy?
- After an incident, are claims partly subsidised or fully reimbursed?
For example:
- Some basic plans cost only AUD $40–50 a month, but provide only partial medical cover.
- Premium plans at AUD $80–120 a month may include ambulance cover and accident compensation.
📌 In short: cheap doesn't mean good value — what matters is the cover you actually need.
3️⃣ Check waiting periods, ambulance cover and special items
Waiting periods are something many people overlook:
- For example, pregnancy, childbirth, dental, psychiatric care and major illnesses — some benefits only take effect after 2–12 months
- Some plans don't include ambulance, or only reimburse it in “emergencies”
⏰ Tip: the earlier you get covered, the better protected you are; the later you leave it, the more likely you are to miss out on a claim.
4️⃣ How to compare plans from different insurers (with comparison tools)
Australia's leading insurers currently include:
- Bupa (external link)
- Allianz Care (external link)
- nib (external link)
- Medibank (external link)
Every insurer's website lists the details, but if you want to compare several plans and premiums at once, try these tools:
🔗 Recommended comparison platforms:
- ✅PrivateHealth.gov.au (the Australian Government's official insurance lookup site) (external link)
- Recommended OVHC comparison platforms
✅OVHC Insurance comparison platform (external link)
Currently the only platform that compares Australia's six major OVHC insurers in one place, including Bupa, Allianz, nib and more. You can get quotes quickly and receive proof of insurance within minutes to meet visa condition 8501.
✅Compare The Market – OVHC comparison tool (external link)
A large insurance comparison platform offering OVHC plan comparisons for many visa types, such as Working Holiday and tourist visas.
✅Budget Policy – OSHC & OVHC comparison platform (external link)
Compares OSHC and OVHC plans across multiple insurers to help you find the plan that suits you best.
✅Get My Policy – OVHC/OSHC comparison platform (external link)
Lets you compare OSHC and OVHC plans from several insurers, with instant quotes and proof of insurance.
📌 Quick tip: what to check when using a comparison platform
Make sure the plan meets your visa requirements: confirm that the plan you choose meets the Australian Government's health insurance requirements for your visa type.
Compare premiums and coverage: premiums and coverage can vary widely between plans, so choose the one that best fits your needs.
Watch for waiting periods and extra cover: some plans have waiting periods or exclude certain services such as dental and optical, so read the policy terms carefully.
With comparison tools, you can clearly see how different insurers compare on:
- Monthly cost
- Coverage
- Ambulance included?
- Waiting period length
That way you can choose the plan that truly fits your needs, without wasting money or taking unnecessary risks!
Choosing the right insurance isn't spending money — it's buying protection and peace of mind.
A little research before you leave can save you much more time, money and stress in Australia.
Next, let's look at an advanced add-on: beyond basic health insurance, what “extra cover” is worth considering?
Budget, job and daily-life preparation beyond insurance is covered in our Complete Guide to a Working Holiday in Australia.
What extra cover can you add beyond insurance? (Advanced add-ons)
(Extra cover for Australian health insurance; recommended travel insurance for Australia)
Basic OSHC and OVHC cover can handle general medical needs, but for people with special needs or who want more comprehensive protection, there are still gaps in cover.
In this section, we'll look at what extra cover you can add, and who should top up their protection.
🧳 Do you need travel or liability insurance?
While OVHC is the core of your medical protection, for certain types of travellers, “travel insurance” and “liability insurance” can be very useful additions:
- 🛫 Travel insurance: suited to short-term visitors, independent travellers and tourist visa holders; it usually includes:
- Compensation for lost or damaged luggage
- Flight delay / cancellation
- Emergency assistance or repatriation
- Personal liability and accident cover
- ⚠️ Public Liability Insurance: suited to people working outdoors, dealing with customers or doing internships; it covers your legal liability and compensation if you accidentally injure someone or damage their property while in Australia
📌 Quick tip: travel insurance is usually a short-term policy (30–180 days). It works well alongside OVHC but isn't recommended as a full replacement.
🦷 When should you add dental or optical cover?
Most OSHC and OVHC plans don't include dental or optical, yet both are extremely expensive in Australia (a single dental clean starts from AUD $200, and glasses from AUD $400).
Dental or optical cover is especially recommended for:
- People with gum disease, cavities or who need dentures
- People with dry eyes or short-sightedness, or who need regular eye tests or glasses
- Plan to stay in Australia for more than 6 months
🎯 Choose a plan that includes “Extras Cover”, or buy a separate dental and optical policy.
🧭 Should long-term stayers consider a multiple-entry plan and extending their insurance?
If any of the following apply to you, we recommend planning ahead for an insurance extension or a multiple-entry plan:
- Plan to extend your Working Holiday or change visas (e.g. WHV → student visa)
- Plan to return home briefly and then come back to Australia (family visits, travel)
- Plan to hold a work visa or apply for a residence visa
📌 If your cover lapses for longer than a certain period, some visas may become invalid, or you may have to serve the waiting periods again.
✅ Suggested solution:
- Use the “auto-renewal” feature
- Or choose a long-term OVHC plan that covers multiple entries and exits
- Renew your insurance 1–2 months in advance before each visa change or extension
The bottom line: basic insurance is the minimum standard, but advanced cover is what really matches your lifestyle and risks. Think it through based on your plans, health and budget, and build the insurance combination that suits you best, so you can live in Australia with more peace of mind and flexibility!
Conclusion | Don't let “saving a little” turn into “losing a lot” — choose the right insurance and travel with peace of mind!
You might think insurance is an “optional” expense, but in Australia, the cost of having no insurance is far higher than you'd imagine.
It's not just about money — it's the key to whether you can live, study and work with peace of mind.
To help you make the right final choice, here's a simple summary table that clarifies the differences between OSHC and OVHC once more 👇
OSHC vs OVHC summary comparison table
| Item | OSHC | OVHC |
|---|---|---|
| Eligible visas | Student visa (Subclass 500) | Working Holiday, tourist, work visas, etc. |
| Mandatory? | ✅ Mandatory (required by law) | ❌ Not mandatory (with some visa exceptions) |
| Coverage | General medical, hospital, prescription medicines (depending on the policy) | More flexible cover: doctor visits, emergency care, ambulance, etc. |
| Add-ons available? | Most require add-on cover for dental, optical, etc. | Most plans offer optional extras |
| Recommended for | International students | Backpackers, workers, travellers |
✅ Practical tip: check your insurance documents before you leave
Before leaving for Australia, make sure you've completed the following:
- ✅ The right type of insurance (meets your visa requirements)
- ✅ The policy covers your entire stay (including before enrolment and after graduation)
- ✅ You've received your Certificate of Insurance for your visa application
- ✅ Understand your policy, the claims process and how to contact customer service
📌 Keep both digital and printed copies of your policy, and save a photo backup on your phone or in the cloud!
🎁 Free insurance quotes & pre-departure resources for Australia
To help you plan your life in Australia more easily, we've put together these resources 👇
- 🔍【Free quotes】Quickly compare OVHC premiums and coverage:
👉 OVHC Insurance comparison platform (external link)
👉Compare The Market
👉Budget Policy
👉Get My Policy
👉 Official insurance lookup (PrivateHealth.gov.au) - 🗣️【Free trial lesson】Build your English before you go, so you're not lost for words at the doctor's:
👉 Book a free English lesson | https://original.ambitious-learner.com
👉 Add our Official LINE Account to ask an advisor | https://lin.ee/DR86vGI
Insurance isn't an expense that holds you back — it's the basic gear that lets you live every day in Australia with confidence and peace of mind.
Remember: the better prepared you are, the more freely you can take on adventures and enjoy the experience abroad.
Wishing you a smooth journey in Australia, and may you come home rich in both learning and life experiences! 🇦🇺✨
For what to sort out once you land, see Your First Week in Australia: A Landing Checklist.
Further reading & free resources
Now that you've read this complete guide to Australian insurance, if you're getting ready for your trip to Australia, don't miss these key resources 👇
📘 Practical English Guide for Working Holiday
From speaking up in interviews and asking about accommodation to everyday phrases for asking for help, learn it all at once and live in Australia without fear of speaking!
👉 Further reading: 【Practical English Guide for Working Holiday】 (internal link)
💰 Australian living costs & money management
A Working Holiday isn't just a holiday — how you spend, save and send money home all takes skill!
👉 Further reading: 【How to plan living costs in Australia: a complete money guide for working travellers】 (internal link)
🆓 Book a free English trial lesson
English not ready before you leave? Don't worry! We offer live one-on-one English lessons designed around Working Holiday, travel and everyday-life situations.
✨ Book a free trial lesson (no pressure, no contract):
👉 Tap here to add us on LINE and book with an advisor:
📲https://lin.ee/DR86vGI
Before you leave for Australia, get your “language × insurance × daily life” sorted all at once, and you'll worry less and explore more.
Bookmark this article so you can quickly find key information before, during and after your trip! 🧭🌏
Want to turn this into an action plan that fits you?
Start with a free trial lesson to pin down your level and next steps.
Free Consultation →Ask us about working holiday prep, English lessons, or job referrals in Australia

